Car Financing for Singapore Gig Workers: 2026 Guide
What if your monthly platform statements were treated with the same respect as a corporate payslip? For many freelancers and PHV drivers in 2026, the reality is often a stack of rejection letters from major banks. It's exhausting to manage a successful gig while facing a mandatory 30% income haircut on your earnings just because your pay isn't fixed. With Category A COE premiums sitting at S$133,009, the pressure to find viable car financing options for gig economy workers sg has never been higher.
You don't have to let strict MAS loan-to-value limits or the daunting 40% downpayment requirement stall your career. This guide explores how you can secure a reliable, fuel-efficient vehicle by looking beyond traditional banking hurdles. We'll examine flexible in-house financing, the impact of the 2026 CPF contribution hikes, and how to calculate the total cost of ownership for a PHV-ready hybrid. You'll discover that securing a vehicle is possible when you partner with experts who understand the unique nature of freelance income. By the end, you'll have a clear roadmap to getting on the road without the typical financial stress.
Key Takeaways
- Learn how to use your IRAS Notice of Assessment and bank statements as valid income proof to replace traditional payslips.
- Compare different car financing options for gig economy workers sg to find the balance between low interest rates and flexible approval criteria.
- Understand how current 2026 COE premiums and MAS loan-to-value limits affect your upfront cash requirements and monthly installments.
- Discover why opting for pre-owned Japanese hybrids provides the best return on investment for full-time PHV drivers.
- Identify the benefits of one-stop financing and insurance solutions that simplify the vehicle ownership process for freelancers.
The Challenge for Gig Workers: Why Banks Often Say No
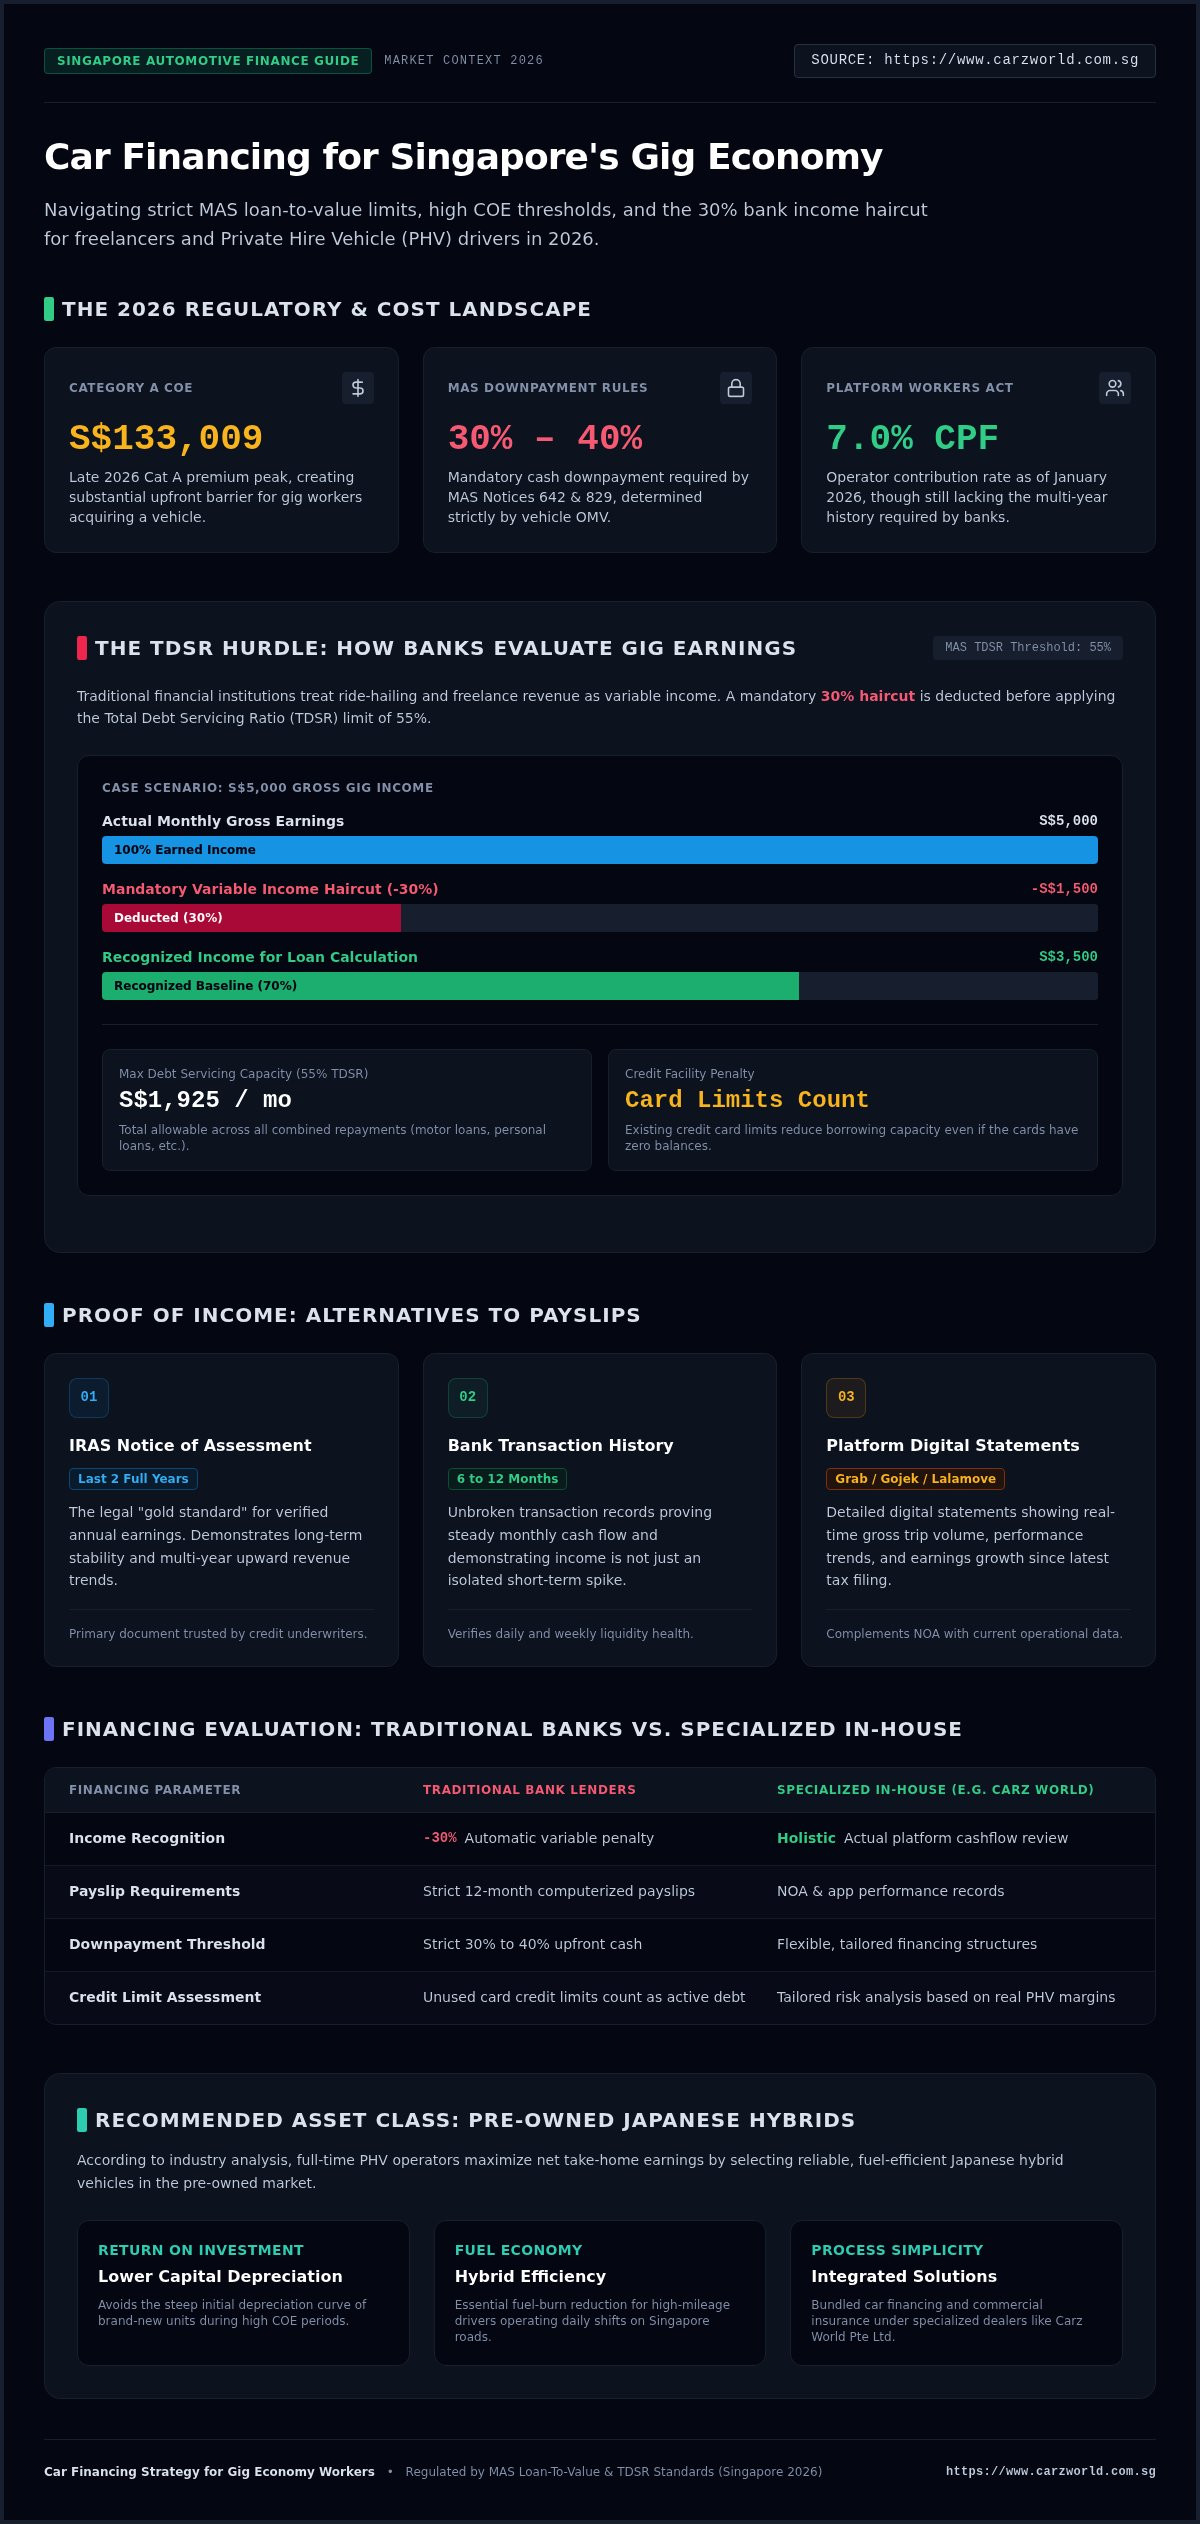
Gig economy car finance in Singapore isn't just about the loan; it's about proving you're a safe bet without a fixed salary. Most traditional lenders view ride-hailing or freelance work as variable income. This classification triggers stricter scrutiny under Monetary Authority of Singapore (MAS) regulations. Because of high Singapore Certificate of Entitlement (COE) prices, which hit S$133,009 for Category A in late 2026, finding accessible car financing options for gig economy workers in Singapore is a common challenge. Banks want to see stability, and they often find it lacking in the gig sector.
MAS Notices 642 and 829 dictate that you must pay at least 30% or 40% upfront in cash, depending on the vehicle's Open Market Value (OMV). For many, this large cash outlay is the first major roadblock. Banks enforce these limits strictly, leaving little room for negotiation if your paperwork doesn't meet their high standards.
To better understand how your income affects your ability to own a vehicle, watch this financial breakdown:
Understanding the TDSR Hurdle
The Total Debt Servicing Ratio (TDSR) is a major hurdle for anyone without a payslip. It limits your total monthly debt repayments to 55% of your gross income. Banks apply a mandatory 30% haircut to gig earnings. If you earn S$5,000, the bank only recognizes S$3,500. This reduced figure makes it much harder to pass the TDSR test, especially if you have existing credit card balances or personal loans. Your credit cards aren't just for spending; their limits count against your borrowing capacity even if you don't use them. Banks want to ensure you aren't overleveraged before they grant a new motor loan.
The CPF Contribution Gap
Traditional banks prioritize applicants with steady employer CPF contributions because they represent job stability. While the Platform Workers Act 2024 has increased operator CPF shares to 7.0% as of January 2026, many freelancers still lack the multi-year history banks demand. Without a 12-month trail of computerized payslips, you're often labeled high risk. This gap is why exploring alternative car financing options for gig economy workers in Singapore becomes essential for staying on the road. Voluntary contributions help, but they rarely carry the same weight as a corporate salary in a bank's automated approval system. Many drivers find that their hard work doesn't translate into creditworthiness in the eyes of a traditional bank, leading them to specialized providers like Carz World Pte Ltd for tailored solutions.
Essential Documentation: Proving Income Without a Payslip
Proving your earnings as a freelancer or PHV driver requires a shift in strategy. Since you don't have a monthly payslip, your goal is to demonstrate a reliable pattern of income over a sustained period. Most lenders look for 6 to 12 months of transaction history to verify that your earnings aren't just a temporary spike. This duration provides a clear picture of your financial health despite the fluctuations inherent in gig work. When exploring car financing options for gig economy workers sg, having a complete documentation folder is the most effective way to build trust with a lender. While banks must follow strict MAS motor vehicle loan restrictions, presenting a transparent financial history makes your application much stronger.
Leveraging Your IRAS Notice of Assessment
Your Notice of Assessment (NOA) from IRAS serves as the ultimate proof of your declared income. Lenders typically request the last two years of NOAs to assess long-term stability and income trends. If your recent earnings have grown significantly since your last tax filing, you should supplement your NOA with current platform statements to show your upward trajectory. The IRAS Notice of Assessment is the gold standard for freelancers because it represents a verified, legal record of your annual earnings that financial institutions trust implicitly.
Alternative Proof of Earning Power
Beyond tax records, your digital footprint on platforms like Grab, Gojek, or Lalamove is incredibly valuable. These apps provide detailed earnings reports that highlight your weekly and monthly performance. Pairing these with 6 to 12 months of bank statements allows you to show a healthy 'float', which is the consistent balance remaining in your account after your daily expenses are paid. This surplus proves you can comfortably handle monthly installments without financial strain.
To make the approval process smoother, you should prepare these items:
- The latest two years of your IRAS Notice of Assessment (NOA).
- 6 to 12 months of bank statements showing regular gig-related deposits.
- Official monthly earnings summaries from your primary platforms (e.g., Grab Driver App).
- A valid Private Hire Car Driver's Vocational Licence (PDVL) if applicable.
At Carz World, we specialize in verifying these non-traditional income streams for our clients. We look at the actual numbers behind your hard work rather than just checking for a corporate letterhead. If you aren't sure if your current paperwork is enough, our team can help you review your car financing options to find a path that works for your specific career stage.
Comparing Financing Routes: Bank vs. In-House vs. Leasing
Choosing how to pay for your vehicle is a strategic decision that directly affects your daily take-home pay. While some drivers prioritize the lowest possible interest rates, others need a low entry barrier to start earning immediately. The legal framework provided by the Ministry of Manpower Platform Workers Act has helped formalize the status of gig workers, but banks still maintain high walls. Bank loans typically offer the lowest flat rates, often between 2.48% and 2.98%. However, their strict adherence to MAS LTV caps and the 30% variable income haircut means many drivers face rejection. For those who can't meet these rigid criteria, exploring alternative car financing options for gig economy workers sg is the next logical step.
In-House Financing: The Flexible Solution
In-house financing is often the most practical route for full-time PHV drivers. Dealers like Carz World have the autonomy to look at your actual earnings rather than just your tax bracket. One of the biggest advantages is speed. While a bank might take a week to process your paperwork, in-house approvals often happen within 24 to 48 hours. This efficiency means you can get on the road and start covering your costs sooner. These loans are also more adaptable. We understand that gig work operates on weekly payouts, so we can often tailor repayment structures that align with your cash flow. It's about finding a balance that supports your business goals without causing financial strain.
Leasing and Rental-to-Own Models
If the 30% to 40% downpayment requirement is too high, rental cars offer a low-risk entry point. Leasing is particularly useful for new drivers who want to test the waters before committing to a 7-year loan. You don't own the asset initially, but you also avoid the heavy upfront capital outlay. Some drivers use a 'Rent-to-Own' model, where they eventually transition from renting to purchasing their vehicle as they build up savings. This route prioritizes immediate cash flow over long-term equity. It's a sensible choice for those who need to start working immediately but lack the significant cash reserves required for a traditional purchase. Ultimately, the best choice among car financing options for gig economy workers sg depends on whether you value immediate ownership or financial flexibility.
Budgeting for Singapore’s Unique Costs in 2026
High Certificate of Entitlement (COE) prices are the single largest factor in your monthly budget. With Category A premiums reaching S$133,009 in late 2026, even an entry-level car carries a heavy depreciation cost. When you evaluate car financing options for gig economy workers sg, you're essentially financing the right to drive as much as the vehicle itself. This means your monthly installment could easily exceed S$1,500 before you've even pumped your first litre of petrol. It's vital to calculate if your daily earnings can comfortably cover this fixed cost before you commit to a long-term loan.
Managing the Downpayment
The upfront cash requirement is strictly determined by the vehicle's Open Market Value (OMV). If the car's OMV is S$20,000 or less, you're required to provide a 30% downpayment. If the OMV exceeds that threshold, the requirement jumps to 40%. For a vehicle with a total price tag of S$160,000, you're looking at a cash outlay of S$48,000 to S$64,000. Saving this amount while paying weekly rental fees can feel like an uphill battle. One practical way to bridge this gap is to leverage the equity in your current ride. By choosing to trade in your vehicle at Carz World Sell, you can significantly reduce the cash you need to bring to the table. It's a methodical way to transition from a personal car to a business-ready asset without draining your entire savings account.
The Reality of PHV Insurance
You can't use standard private motor insurance for commercial gig work. Doing so risks having your claims rejected and your vocational license revoked. PHV insurance is significantly more expensive because of the high mileage and increased risk profile associated with ride-hailing. Z10 refers to a private car registered for self-drive rental or private hire use, requiring a specific commercial-use endorsement from your insurer. Beyond insurance, you must budget for the 9% GST on all servicing and the tiered road tax. These running costs are the silent drains on your profit margins that often catch new drivers off guard.
High-mileage driving means you'll hit service intervals much faster than the average driver. You'll likely need an oil change and a safety check every two to three months. Don't forget to factor in the cost of tires, brake pads, and the eventual hybrid battery replacement if you're buying a used model. Totaling these up helps you see the real cost of ownership beyond just the interest rate. Exploring various car financing options for gig economy workers sg is only the first step; maintaining the asset is what keeps your business profitable over the long term.
Ready to see how the numbers stack up for your next vehicle? Consult our financing experts today to get a transparent breakdown of all ownership costs.
Finding the Right Vehicle at Carz World
Selecting the right vehicle is the final piece of the financial puzzle. For a PHV driver, the car is a tool for generating income. Efficiency is everything. High COE prices in 2026 mean you can't afford a car that drains your profits at the pump. We recommend Japanese hybrids because they offer the best balance of reliability and low running costs. Choosing a vehicle that holds its value helps ensure your long-term business remains profitable.
Fuel Efficiency and ROI
High-mileage drivers can save thousands of dollars annually by switching to a hybrid. Petrol prices in Singapore remain high, with excise duties around 66¢ to 79¢ per litre. A hybrid like the Honda Vezel or Toyota Prius significantly reduces your fuel overheads compared to pure internal combustion engines. The Honda Vezel remains a top choice in the local market because of its spacious interior and excellent fuel economy. When you choose a car with a high ROI, your monthly repayments become much easier to manage. Your vehicle choice is directly tied to the success of your car financing options for gig economy workers sg.
The Benefits of Pre-Owned
Buying pre-owned cars is a strategic move for gig workers. New cars lose a large chunk of value the moment they leave the showroom. By choosing a certified used vehicle, you let the first owner take that depreciation hit. This lowers your total loan amount and your monthly installments. Every car at Carz World Pte Ltd undergoes a rigorous inspection to ensure it meets our high standards for safety and performance. We certify our vehicles so you can drive with confidence, knowing the asset is reliable.
Why Carz World Pte Ltd is the Trusted Partner
We understand that freelancers face unique hurdles when looking for a car. Our team at Carz World Pte Ltd specializes in managing complicated car financing options for gig economy workers sg. We don't use high-pressure sales tactics. Instead, we focus on being a methodical and honest partner in your transaction. We handle everything from the initial viewing to the final insurance endorsement. This one-stop approach saves you time and reduces the stress of coordinating multiple parties. It's our goal to make the entire process feel like a seamless experience.
Visit our showrooms at Vertex @ Ubi or Alexandra Central to see our extensive inventory of Japanese and Korean hybrids. Our staff members at Carz World Pte Ltd are ready to help you find a vehicle that fits your budget and your career goals. We're here to guide you through the process with professional, customer-centric service.
Taking the Next Step Toward Vehicle Ownership
Securing a car in 2026 doesn't have to be a source of constant stress. You've seen that having the right documentation, such as your IRAS NOA and platform statements, is the foundation for a successful application. While banks often maintain rigid rules, there are flexible car financing options for gig economy workers sg that cater to your specific lifestyle. By choosing a fuel-efficient hybrid, you protect your daily profit margins from high running costs and elevated COE premiums.
At Carz World, we provide a professional and trustworthy service designed to simplify the entire process. We specialize in hassle-free financing for freelancers, ensuring you get on the road without the typical paperwork headache. Our reputation is backed by over 100+ positive client testimonials from drivers who have successfully built their careers with our support. We focus on making complex logistical steps feel like a seamless experience for every customer.
Don't let traditional banking hurdles hold you back from your career goals. We're here to help you find a vehicle that fits your budget and earning potential. Browse our wide range of gig-ready used cars today and experience a reliable path to ownership. You have the drive to succeed, and we have the expertise to get you there.
Frequently Asked Questions
Can I get a car loan if I just started as a Grab driver last month?
You'll likely find it difficult to secure a bank loan with only one month of history. Most lenders require at least six months of platform statements or a Notice of Assessment to verify your income stability. However, in-house car financing options for gig economy workers sg are often more flexible for those just starting out. We recommend keeping detailed records of your daily earnings and bank deposits to build a strong case for your repayment ability.
What is the minimum downpayment required for a used car in Singapore?
The minimum downpayment is determined by the vehicle's Open Market Value (OMV) as set by MAS. If the OMV is S$20,000 or less, you must provide a 30% cash downpayment. For vehicles with an OMV above S$20,000, the requirement increases to 40%. This rule applies to both new and pre-owned cars. Budgeting for this upfront cost is essential, as it represents the largest initial hurdle for most Singaporean drivers.
Is in-house financing safe for gig economy workers?
In-house financing is a safe and reliable choice when you work with established, CaseTrust-accredited dealerships like Carz World. It's a common alternative for those who don't meet the rigid criteria of traditional banks. Reputable dealers provide transparent contracts and clear interest rate breakdowns. This route is often preferred by freelancers because it offers higher approval rates and faster processing times. It's a professional solution that helps you secure a vehicle without the stress of bank rejections.
Does my credit score (Bureau report) matter for in-house car loans?
While your credit score is reviewed, in-house lenders place much more weight on your current earning capacity and bank statement history. Banks often reject applications automatically based on Bureau reports, but in-house teams take a more holistic view of your financial health. They understand that gig workers may have different credit profiles. Having a steady "float" in your bank account is often more persuasive than a perfect credit score in these specialized financing scenarios.
Can I use my car for both personal use and PHV work?
You can certainly use your vehicle for both purposes, provided it's registered correctly. You must register the car under the Z10 or Z11 classification for private-hire use. Additionally, you need a commercial insurance policy that covers both personal and PHV activities. Standard personal motor insurance will not cover you during platform work. Ensuring you have the right commercial endorsement is vital for protecting your asset and staying compliant with Singapore's road regulations.
What happens if my gig income fluctuates-can I restructure my loan?
Traditional bank loans are generally fixed and don't offer much flexibility if your income drops. This is why we emphasize the importance of the 30% income haircut during your initial budgeting phase. In-house lenders may be more approachable for a conversation, but loan restructuring is not a standard feature. It's best to choose a monthly installment that you can comfortably afford even during slower weeks on the platform to maintain financial ease.
Are there age limits for cars used in the gig economy?
Yes, there are specific age limits you must follow. The Land Transport Authority (LTA) allows cars to be driven for 10 years, with the option to renew the COE. However, ride-hailing platforms like Grab or Gojek often have stricter requirements, typically limiting vehicles to 10 or 12 years of age from the original registration date. When looking at car financing options for gig economy workers sg, it's wise to select a younger pre-owned vehicle to maximize its working life.
How does the COE rebate work if I sell my car early?
If you decide to deregister or export your car before the COE expires, you're entitled to a COE rebate. This rebate is calculated pro-rata based on the remaining months and days left on your 10-year cycle. The refund is issued by the LTA and can help offset the outstanding balance of your car loan. It's a useful financial safety net if your circumstances change and you need to exit your vehicle commitment earlier than planned.
Disclaimer
This content is provided for general informational purposes only. Readers are encouraged to independently verify important information.
In Same Category
- Car Financing for Singapore Gig Workers: 2026 Guide
- Financial Checklist Before Buying a Car in Singapore: 2026 Expert Guide
- Calculating the Real 5-Year Cost of Car Ownership in Singapore (2026 Guide)
- 2026 Guide: Planning for a Second Family Car in Singapore
- Used Cars for Sale in Tampines: 2026 Buyer's Guide
Related by Tags
- Car Financing for Singapore Gig Workers: 2026 Guide
- 2026 Guide: Planning for a Second Family Car in Singapore
- Mercedes C-Class Singapore Guide 2026: Specs, COE, and Buying Tips
- Honda Civic Singapore: 2026 New & Pre-Owned Guide
- Mazda 3 Singapore Guide 2026: Specs, Prices, and Buying Tips
- Hyundai Ioniq 5 Singapore: The Definitive 2026 Buying & Ownership Guide
- Why Carz World is Your Trusted Used Car Dealer in Singapore (2026 Guide)
- Honda Odyssey Singapore: 2026 Family Buying Guide
- Used BYD Atto 3 Singapore: The Ultimate 2026 Buyer's Guide to Value and Reliability