Getting Car Finance as a Freelancer in Singapore: 2026 Guide
A freelancer’s job title doesn’t tell the whole story. A clear record of cash flow can help explain how reliably you can meet repayments. If you’re getting car finance as a freelancer in Singapore, the challenge is often showing how variable earnings add up to sustainable income.
It’s understandable to be unsure what a provider will ask for. Freelance income can change from month to month, and documentation requirements and financing terms may differ between providers. Preparing a straightforward picture of your income, expenses and savings can help you approach those conversations with greater confidence.
This 2026 guide explains how to organise income evidence, including tax, business and banking records a provider may request, and what to ask when comparing financing routes. It also covers how to set a repayment budget that leaves room for quieter months before choosing a car. Carz World offers pre-owned and brand-new vehicles, as well as vehicle financing enquiries. Confirm available arrangements and terms directly with the relevant provider.
Key Takeaways
- When getting car finance as a freelancer in Singapore, present a clear record of income and cash flow rather than relying on isolated proof of earnings.
- Ask your chosen provider which tax, business and banking records it accepts, as documentation requirements can vary.
- Compare offers using written terms, eligibility conditions and total repayment obligations. Confirm rates, fees and tenure directly.
- Set a repayment budget that allows for slower months, then check provider requirements before submitting accurate, consistent application details.
- Assess pre-owned and brand-new cars against your budget, expected use and ownership obligations before choosing a suitable option.
Getting car finance as a freelancer in Singapore: what lenders may assess
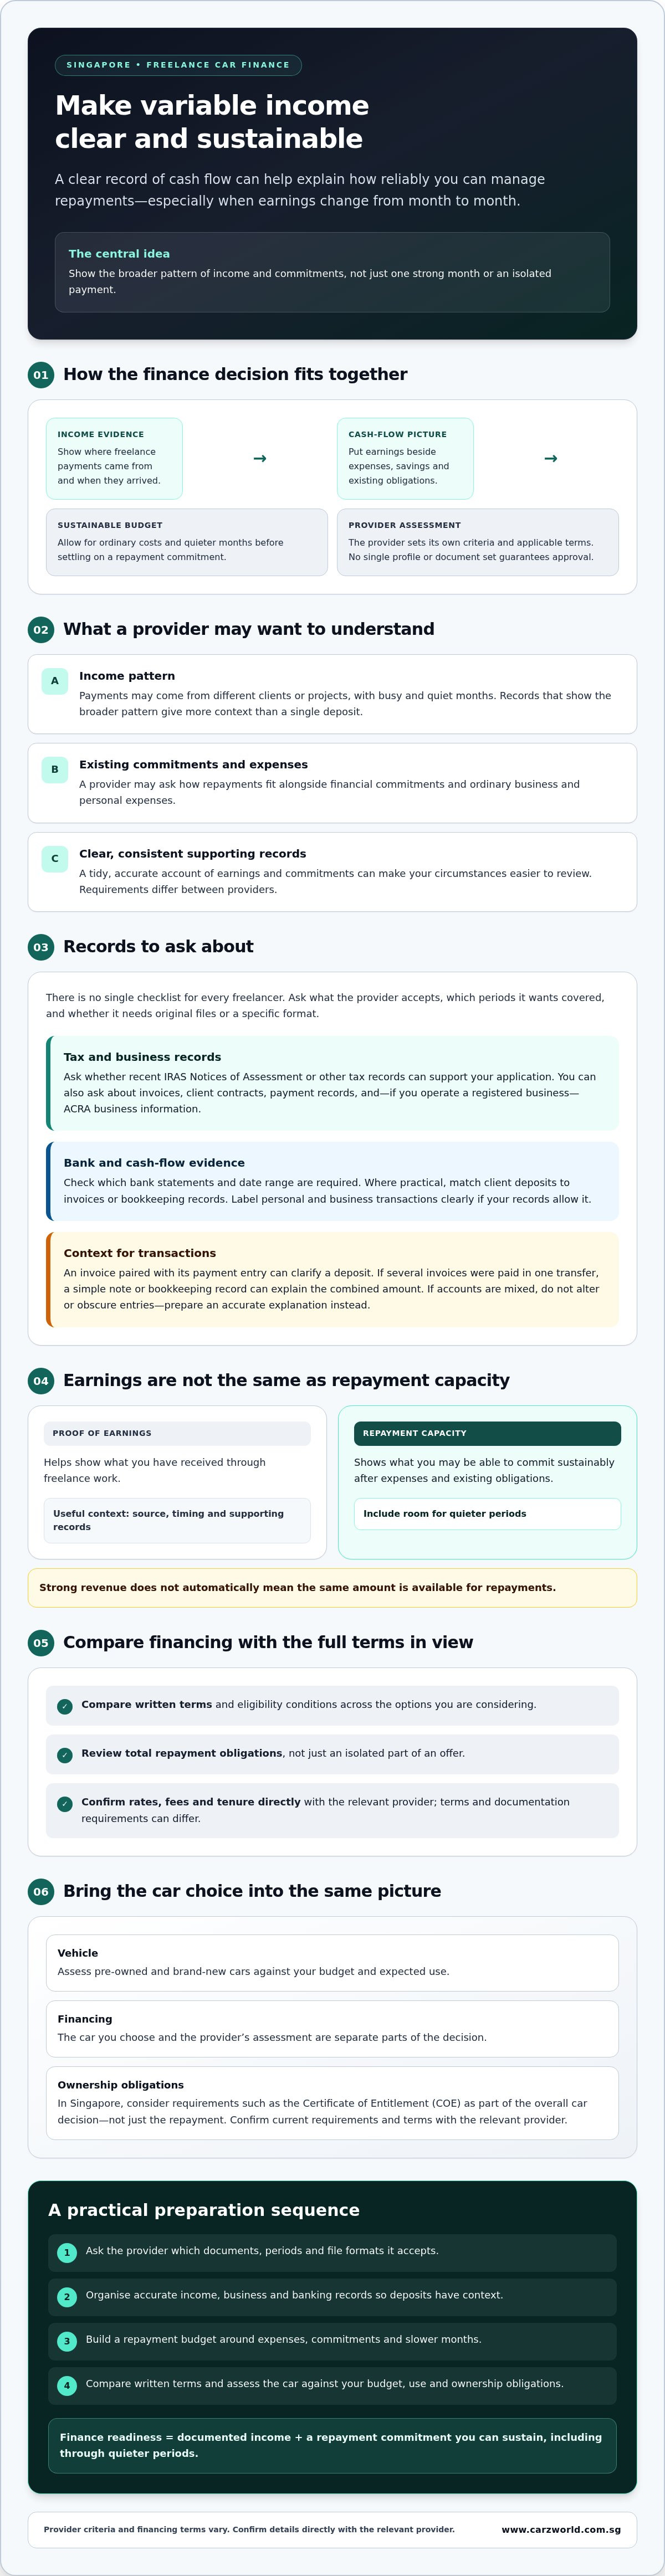
Freelance status alone doesn’t show whether you can manage a car repayment. A provider may look at the wider picture: how income comes in, what financial commitments you already have and whether your supporting records make your circumstances clear. Assessments vary by provider, so no single profile or set of documents guarantees approval.
Car finance helps fund a vehicle purchase. The car you choose and the finance provider’s assessment are separate parts of the decision. The provider considers your application and, if it agrees to proceed, sets out the applicable terms. In Singapore, remember to consider ownership requirements such as the Certificate of Entitlement (COE) as part of the overall car decision, not just the repayment. Confirm current requirements and terms directly with the relevant provider.
Why variable freelance income can raise questions
A salaried applicant may be able to show regular payslips. A freelancer might instead receive payments from different clients or projects, with some months busier than others. That uneven pattern can make it harder to show what income is available for repayments, especially if the evidence is scattered across accounts or records. A quiet month alone doesn’t describe a full year of earnings, but providers may need enough information to understand the broader pattern.
What a finance provider may want to understand
Expect questions about income consistency, existing financial commitments and your ability to manage repayments alongside ordinary business and personal expenses. Providers set their own criteria and may request different supporting documents. Check their requirements before applying rather than assuming one checklist applies everywhere.
Finance readiness means documented income and a repayment commitment you can sustain, including through quieter periods. If you’re getting car finance as a freelancer in Singapore, the practical aim is to present a clear, consistent account of earnings and commitments. Share accurate information and ask the provider how it assesses variable income before choosing a car or relying on an assumed outcome.
Which documents can help show freelance income in Singapore?
There isn’t one document checklist for every freelancer or finance provider. Before collecting paperwork, ask the provider what it accepts, which periods it wants covered and whether it needs original files or specific formats. The examples below can help you prepare, but they aren’t universal requirements.
A tidy set of records is easier to review than scattered screenshots. Aim to show where payments came from, when they arrived and how they relate to your freelance work. This gives a provider more context than a single deposit or a strong earning month on its own.
Income and business records to ask about
Ask whether recent IRAS Notices of Assessment or other tax records can support your application. You can also check whether the provider will consider invoices, client contracts and payment records to explain work completed and income received. If you operate a registered business, ask whether it needs ACRA business information. The provider decides which documents are relevant to its assessment.
Keep related records together where possible. For example, an invoice paired with its matching payment entry can clarify a deposit that might otherwise be difficult to identify. If a client pays several invoices in one transfer, a simple note or bookkeeping record can explain the combined amount.
How to organise bank and cash-flow evidence
Ask which bank statements and date range the provider wants. Gather the relevant statements, then compare client deposits with invoices or bookkeeping records where practical. Label personal and business transactions clearly if your records allow it. If accounts are mixed, don’t alter or obscure entries. Prepare an accurate explanation for transactions that may need context.
Proof of earnings shows what you’ve received; proof of repayment capacity shows what you can sustainably commit after existing expenses and obligations. That distinction matters when getting car finance as a freelancer in Singapore. Strong revenue doesn’t automatically mean the same amount is available for repayments. Build a realistic view of cash flow, including quieter periods, before deciding what commitment may fit.
Income documents help explain your finances, while Singapore’s car-loan rules are a separate part of the picture. Review the official MAS car loan rules and confirm current terms, eligibility criteria and document requirements directly with your chosen provider. Requirements can vary, so ask before submitting an application.
How to compare car-finance options when your income fluctuates
A headline repayment or rate doesn’t show whether an offer suits freelance cash flow. Compare written terms side by side, including eligibility conditions and total repayment obligations. Rates, fees, tenure, required documents and other terms vary by provider. Confirm each detail directly, and don’t rely on verbal estimates alone.
When getting car finance as a freelancer in Singapore, test the proposed commitment against a slower month, not just a strong one. Use a conservative view of income after business costs and existing commitments. Then account for ownership expenses such as insurance, road tax and maintenance. Ask yourself whether repayments would remain manageable if a client paid late or work temporarily slowed, without relying on savings meant for essential expenses.
Questions to ask before comparing finance offers
Ask each provider what income evidence it accepts from freelancers or business owners, and whether its eligibility conditions fit your circumstances. Request a written breakdown using the same questions for every offer. Clarify the repayment schedule, all applicable fees, conditions and what may happen if a payment is missed. Check the official MAS car loan regulations for the regulatory framework, then confirm with the provider how the rules apply to the specific offer.
| Comparison point | Question to ask | Provider’s answer |
|---|---|---|
| Freelance income evidence | Which records do you accept, and what period should they cover? | ________________ |
| Eligibility | What conditions apply to my application? | ________________ |
| Repayments and total obligations | What is the schedule and total amount payable over the agreement? | ________________ |
| Fees and missed payments | What charges or consequences may apply? | ________________ |
| Terms and conditions | What tenure and other conditions apply? | ________________ |
Build an affordability buffer for uneven earnings
Set your budget using income you can reasonably expect in less productive periods, rather than your strongest recent month. Include regular business costs, personal commitments and vehicle ownership expenses before deciding what repayment could fit. Keep an emergency buffer where possible. It can help cover essential outgoings when client work pauses or payments arrive later than expected, without assuming every month will match your average.
Once you’ve set a sustainable budget, you can explore vehicle options with Carz World. Confirm any financing arrangements and terms directly with the relevant provider before making a decision.
How to prepare a stronger car-finance application as a freelancer
A clear application starts before you contact a provider. Work through the steps in order so you know what repayment you can manage, what information you have ready and what you still need to confirm. Getting car finance as a freelancer in Singapore isn’t about presenting your income as perfectly even. It’s about describing your circumstances accurately and consistently.
- Estimate your budget. Use a conservative view of income, account for regular commitments and decide what repayment could remain manageable during slower periods.
- Gather your records. Organise the documents you have that help explain your income and business activity.
- Check provider requirements. Ask what records are accepted, what eligibility conditions apply and what checks or steps to expect.
- Submit your information. Provide complete, consistent details and answer follow-up questions accurately.
Before you speak with a finance provider
Prepare a concise overview of recent income patterns and recurring business expenses. List your current financial commitments, then calculate what you could allocate to a car without relying on your strongest earning month. Bring questions about accepted documents, eligibility, checks, expected timelines and next steps. These details differ between providers, so asking first can help you avoid preparing the wrong information or treating an estimate as a firm decision.
Be ready to explain changes in your work, such as a shift in client mix or a gap between projects. Don’t omit a commitment or adjust figures to make the application appear stronger. Clear explanations are more useful than numbers that don’t match your records.
During and after the application
Submit the information requested and check that names, dates and figures are consistent across your forms and supporting records. If something has changed or a provider asks for clarification, respond promptly and explain it plainly. Before agreeing to any arrangement, read the written terms carefully, including the repayment schedule, conditions and applicable charges. Ask the provider to explain anything you don’t understand.
An initial or indicative assessment isn’t a guarantee. The provider makes the final decision after reviewing the application and any required information. Keep that distinction in mind before committing to a vehicle or making plans based on an expected outcome.
Carz World offers vehicle financing among its related services, but it isn’t the lender and can’t guarantee approval. Ask Carz World about available vehicle-finance assistance, then confirm the provider, process, requirements and terms directly before proceeding.
Choose a car and financing route that fit freelance life
The right car isn’t necessarily the one that qualifies for the largest finance amount. Choose based on what you need the vehicle for, how often you expect to use it and what ownership commitment remains comfortable when freelance income dips. The aim of getting car finance as a freelancer in Singapore is to find a vehicle and repayment arrangement that fit your real cash flow, not just an optimistic month.
Match vehicle choice to variable income
Compare pre-owned and brand-new cars against your budget and expected use. A pre-owned car may be worth considering if it better fits the spending limit you’ve set, while a brand-new car may suit buyers who prefer to compare that purchase route. Neither category is automatically the better choice. Check the specific vehicle information and ask what ownership obligations to factor in. Vehicle age, how you plan to use the car and expected upkeep can all affect the wider budget.
Before deciding, revisit your figures using a lower-income scenario. Include repayments alongside insurance, road tax, maintenance and other commitments, and leave room for delayed client payments where possible. If that budget feels tight in a quiet period, consider a different vehicle or postpone the decision rather than stretching to the maximum amount offered.
Once you have a sustainable budget, you can browse Carz World’s pre-owned cars as one way to explore suitable options. If you’re comparing both categories, Carz World also offers brand-new cars. Check current vehicle details directly before making a choice.
What to clarify with a dealership
Ask what vehicle-finance assistance may be available and which parts of the process, eligibility and terms must be confirmed by the finance provider. Carz World offers vehicle financing among its related services, but it isn’t a lender and can’t promise approval. Confirm the provider and process before relying on any indicative information.
Request written details about the vehicle and any finance-related conditions. Clarify what is included in the proposed arrangement, which costs or obligations sit outside it, and whether details may change subject to provider assessment. Review the written terms carefully and ask questions before agreeing. Clear answers make it easier to compare a car’s overall commitment with your freelance budget.
Take your time choosing. If you’re weighing pre-owned and brand-new options or have questions about vehicle-financing enquiries, speak with Carz World about available vehicle choices and assistance. Confirm all financing criteria and terms directly with the relevant provider, and choose only when the commitment feels manageable across busy and slower periods.
Move forward with a clear, sustainable plan
Freelance income can be uneven, so focus on showing the full picture rather than judging affordability by one busy or quiet month. Organised income records help explain your earnings, while a realistic budget should leave room for existing commitments and slower periods.
Before choosing a car, compare written finance terms and confirm each provider’s requirements directly. The right option is one that fits your work needs and remains manageable across changing income, not simply the largest amount you may be offered. That’s a practical foundation for getting car finance as a freelancer in Singapore.
Carz World offers pre-owned and brand-new vehicles in Singapore, with vehicle financing listed among its related services. Explore suitable cars and discuss your finance enquiry, then confirm current arrangements, eligibility and terms with the relevant provider. Take the next step at a pace that feels comfortable, with a clear budget and confidence in your decision.
Frequently Asked Questions
Can freelancers get car finance in Singapore?
Freelancers can apply, but freelance work alone doesn’t determine whether an application will be accepted. Each provider assesses applications using its own criteria and may consider income evidence, existing commitments and repayment capacity. Before applying, ask how the provider evaluates variable earnings and which records it accepts. Approval, terms and documentation depend on the provider and your individual circumstances, so don’t treat another applicant’s experience as a guarantee.
What documents do self-employed applicants need for car finance in Singapore?
There isn’t a universal document list, so request a current checklist from your chosen provider. It may ask about tax records, bank statements, invoices or business information, but these aren’t automatic requirements for every application. Organise records that help explain where your income comes from and when it arrives. Also ask whether documents must cover a particular period or meet specific submission requirements before you apply.
How do lenders assess freelance income for car finance?
A provider may review income records, payment regularity, existing financial commitments and whether proposed repayments appear sustainable. It may consider the overall application rather than relying on one document or a single month’s income. Assessment methods and thresholds differ, so ask shortlisted providers how they evaluate variable or seasonal earnings. Prepare an accurate overview of your income pattern, but don’t assume it guarantees a particular decision or offer.
Can I apply for car finance if my freelance income changes every month?
You can ask providers how they assess fluctuating income. Changing earnings alone don’t determine the outcome. For getting car finance as a freelancer in Singapore, organised records can help explain stronger and quieter periods, while a conservative personal budget shows what repayments may be manageable. Include ongoing ownership costs in your calculations. Before committing to a vehicle, confirm the provider’s eligibility criteria, accepted documents and current terms directly.
How much income do I need to qualify for car finance in Singapore?
There’s no single income figure that can be presented as a universal qualification rule. Providers may consider your income evidence, current commitments, vehicle details and their own criteria. Ask each provider about its requirements rather than relying on an online threshold or another applicant’s experience. Separately, estimate affordability using income you can reasonably expect in slower periods, and account for ownership costs before deciding what commitment feels sustainable.
Does a freelancer need an ACRA-registered business to apply for car finance?
Don’t assume ACRA registration is required for every application, or that having a registered business guarantees eligibility. Requirements depend on the provider and your circumstances. Ask whether ACRA business information is relevant to your application and what alternative evidence may be accepted if you work independently without a registered business entity. Confirm the exact document list before applying, and make sure the information you provide accurately reflects how you earn income.
Should freelancers choose a cheaper car to improve their finance application?
A less expensive car may reduce the overall financial commitment, but it doesn’t guarantee approval or determine how a provider will assess your application. Compare the full ownership budget, including insurance, road tax and maintenance, against income during quieter months. Choose a vehicle that remains manageable under conservative assumptions, rather than stretching to the largest amount offered. Confirm the finance terms directly with the provider before committing to a purchase.
Disclaimer
This content is provided for general informational purposes only. Readers are encouraged to independently verify important information.