What to Do If Your Car Loan Is Rejected and Find Options
A rejected car loan is a reason to pause and find out what needs to change. If you’re wondering what to do if my car loan application is rejected, start by asking the lender for its reasons within 60 days and reviewing the decision letter. Then check your application details, credit history and monthly debt commitments before deciding whether to reapply or adjust your budget.
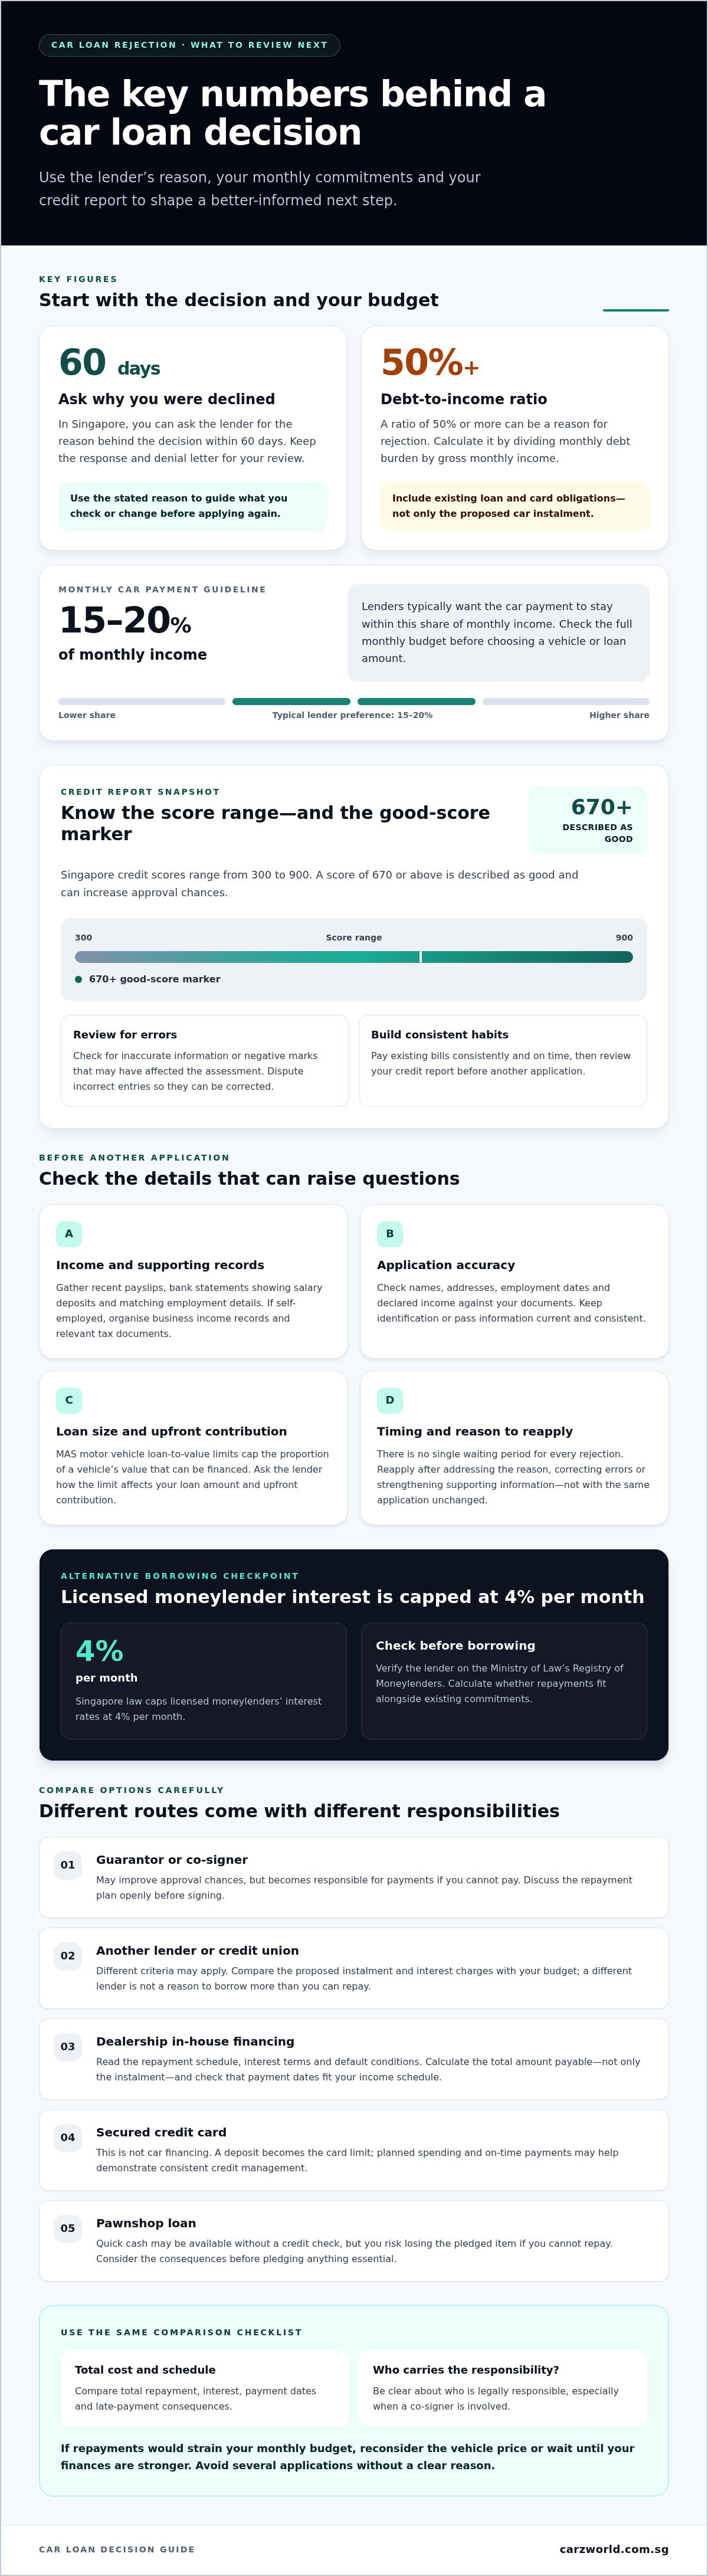
It’s understandable to feel stuck when financing falls through, especially if you need a car soon. But applying again without understanding the decision may leave the same concerns unresolved. A debt-to-income ratio of 50% or more can be a reason for denial, while lenders typically want a car payment to be no more than 15% to 20% of monthly income.
This guide explains how to discuss a rejection with your lender, identify possible issues in your credit report or application, and carefully consider other financing options. You’ll also learn how to compare a different vehicle budget with the overall cost of borrowing, so your next step is based on clear information rather than pressure.
Key Takeaways
- Ask your lender for the reason behind the decision within 60 days, then use the denial letter to plan your next steps.
- Review your application and credit report for missing details, errors, or negative marks that could have affected the assessment.
- Revisit your budget and consider whether a smaller loan would better fit your income and existing monthly commitments.
- Compare possible alternatives carefully, including the responsibilities a co-signer takes on if you can’t make payments.
- Explore a vehicle that better matches your budget before making another financing application.
1. What to do if your car loan application is rejected?
If you’re asking what to do if your car loan application is rejected, first identify the issue before submitting another application. Review the lender’s decision letter, then check your income, monthly debts, credit history and application details for anything that may have affected its assessment.
Show income stability with clear, consistent records. Gather recent payslips, bank statements showing salary deposits, and employment details that match your application. If you’re self-employed, organise business income records and relevant tax documents. These can help explain how you earn and whether your income can support regular repayments. Make sure the identification or pass information you provide is current and consistent across your documents.
Check every field before applying again. A misspelled name, outdated address, incorrect employment date or mismatch between declared income and supporting records can raise questions. Compare the form with your documents line by line. If your employment or income has changed, provide accurate current details instead of copying an older application.
Calculate your debt-to-income ratio by dividing your current monthly debt burden by your gross monthly income. A ratio of 50% or more can be a reason for rejection. Lenders typically want the car payment to stay within 15% to 20% of monthly income. Include existing loan and card obligations when assessing your budget, not just the proposed instalment.
MAS motor vehicle loan-to-value limits cap the proportion of a vehicle’s value that can be financed. The applicable limit affects the loan amount and upfront contribution, so ask the lender to explain how it applies to your vehicle and proposed loan.
There’s no single waiting period that suits every rejected application. Reapply after addressing the reason for the decision, correcting errors or strengthening your supporting information, rather than resubmitting the same application unchanged.
To improve your credit score, pay existing bills consistently and on time, and review your credit report for inaccurate information. Singapore credit scores range from 300 to 900; a score of 670 or above is described as good and can increase approval chances. Check the report before applying, and dispute incorrect entries so they can be corrected.
A high debt-to-income ratio, low credit score, negative items on a credit report or request for too much money may lead to a rejected car loan application. Consider these possibilities alongside the lender’s stated concerns, and focus a new application on resolving the specific issue rather than changing details without a clear reason.
2. Alternatives after a loan application is denied
A rejection doesn’t mean every financing option is closed, but each alternative comes with different costs and responsibilities. Compare repayment terms, total interest and the consequences of missed payments before making another commitment. Avoid submitting several applications without a clear reason. First decide which option fits your income and addresses the reason for the rejection.
Can you get a car loan in Singapore with bad credit, irregular income or a guarantor? A lender may consider your credit history, ability to repay and the guarantor’s financial position. A guarantor or co-signer may improve your chances of approval, but becomes responsible for payments if you can’t pay.
A credit union or another lender may assess applications using different criteria. Ask what information they need to review your income and existing debt, then compare the proposed instalment and interest charges with your budget. A different lender is no reason to borrow more than you can repay. Review your credit report to understand what may affect another assessment.
Some dealerships offer buy-here-pay-here financing, where the dealership provides in-house financing. In other markets, alternative arrangements such as rent-to-own programs—like those offered by Rent To Buy A Car—illustrate how drivers can secure a vehicle when conventional bank lending falls through. Before agreeing, read the repayment schedule, interest terms and default conditions. Calculate the total amount payable, not just the instalment, and make sure the repayment date fits your regular income schedule.
A secured credit card is another way to build credit history, but it isn’t car financing. You provide a deposit, which becomes your card limit. Use the card for planned spending and make payments on time. This may help demonstrate consistent credit management before you apply for a car loan again.
Licensed moneylenders are a separate borrowing option, not a substitute for comparing car loan terms. Singapore law caps licensed moneylenders’ interest rates at 4% per month. Before borrowing, check that the lender appears on the Ministry of Law’s Registry of Moneylenders, and calculate whether repayments fit alongside your existing commitments.
A pawnshop loan can provide quick cash without a credit check, but you risk losing the pledged item if you can’t repay. Consider what losing it would mean before using it to raise funds. Don’t pledge something essential to your work or daily needs without a clear repayment plan.
Compare alternatives using the same checklist: total repayment, interest, payment dates, late-payment consequences and who is legally responsible. If a co-signer is involved, discuss the repayment plan openly before signing. If the payment would strain your monthly budget, reconsider the vehicle price or wait until your finances are stronger instead of choosing a longer or less suitable commitment.
3. Discussing denial reasons with the lender
Contact the lender promptly and ask for the specific reasons behind the denial. In Singapore, you can ask why your car loan application was rejected within 60 days. Keep the response, denial letter and any supporting documents together. These records help you distinguish a correctable application issue from a concern about affordability or credit history.
Read the denial letter before calling or writing. Note each reason separately, such as missing information, an income concern, existing debt or a credit report issue. If the letter uses general wording, ask the lender to explain which part of your application led to the decision. Don’t guess at the reason or change details without evidence.
Can a Singapore bank or finance company reconsider a rejected car loan application? Yes. You can ask the lender to review its decision, especially if you can provide corrected or additional information. Reconsideration isn’t automatic, so ask what documents or changes would support a fresh assessment.
Prepare a short, factual request. Include your application reference, the decision date and the reason you want clarified. If you found a mismatch, identify the exact field and attach the corrected record. For example, if your stated monthly income differs from a payslip, explain the difference and provide documents showing the accurate figure.
Use focused questions to make the discussion useful:
- Which specific factor led to the denial?
- Did missing or inconsistent information affect the assessment?
- Was the concern related to income, monthly debt or credit history?
- What information would be relevant if you apply again?
Ask the lender to distinguish between the facts and the next steps. A document error can be corrected directly, while a debt or credit concern may require changes to your finances before another application. If the lender identifies an inaccurate credit entry, obtain your credit report and follow the process for disputing that information.
Keep a record of each conversation, including the date, staff member’s name and any documents requested. Send only information relevant to the application, and make sure every figure matches its supporting record. If the lender confirms an error, request written confirmation of the corrected detail or next review step.
Don’t submit an unchanged application simply because the first conversation was brief. Use the lender’s explanation to decide whether to correct an error, provide further evidence or adjust the amount you plan to borrow. A clear reason and documented response give you a more practical basis for deciding what to do next.
4. Applying for a smaller loan
A smaller loan may address a lender’s concern if the requested amount exceeds what your income can support. Start with the reason for the rejection, then calculate a borrowing amount that fits your monthly budget. Reducing the amount alone won’t fix inaccurate application details or a credit issue, so address those separately before applying again.
Work backwards from a manageable payment. Lenders typically want a car payment to be no more than 15% to 20% of monthly income. Compare that range with your existing monthly commitments, then decide what payment leaves room for regular household expenses. This gives you a budget ceiling before you look at another vehicle or request a revised loan.
A larger deposit can reduce the amount you need to borrow. First calculate how much you can put down without using money set aside for essential expenses. Subtract the deposit from the vehicle’s purchase price to estimate the amount to finance. A larger deposit means a smaller loan request. Keep enough savings for other planned costs.
Consider a lower-priced vehicle if the revised loan still requires an uncomfortable payment. Compare options by purchase price and the amount you would need to finance, not by monthly instalment alone. A longer term can make the instalment appear lower while increasing total interest. A longer repayment term can make the monthly payment seem more manageable while extending how long you repay.
Before changing the loan term, compare the full repayment schedule. Check the instalment, interest charges and total amount payable. Ask the lender to show how a smaller principal changes those figures while keeping the term comparable. This helps distinguish genuine savings from a lower payment achieved mainly by borrowing for longer.
Use this sequence to prepare a revised request:
- Set a monthly payment limit based on income and existing obligations.
- Choose a vehicle within that budget and calculate the deposit you can afford.
- Estimate the smaller loan amount and compare repayment schedules.
- Provide the lender with updated figures and supporting documents.
Prequalification can indicate the loan amount and interest rate you may receive if your application is successful. Use those details to compare a revised budget, not to justify stretching your spending. If a smaller loan still leaves too little room for other commitments, wait until your finances can support the payment rather than choosing an extended term just to make it seem affordable.
5. Finding out why a car loan application was rejected
Start with evidence, not assumptions. A low credit score, poor credit history, negative credit report items, high debt commitments or incorrect application details can all affect approval. The lender’s denial letter is the first place to look for a reason specific to your application.
Separate each stated reason and match it to a record. If the lender cites income, compare your application with payslips and bank statements. If it mentions existing debt, review your monthly repayments. If it points to credit history, inspect your credit report for missed payments, bankruptcy records or other negative marks.
A rejected application is the lender’s decision, not proof by itself that your credit report contains a negative mark. Review your report to see what information it includes and identify any entry that appears inaccurate.
Use the report as a record to investigate, not as a substitute for the lender’s explanation. Check your personal details, account history and payment information. An unfamiliar account or incorrect missed-payment entry may need to be disputed so the report can be corrected. Keep copies of the report and any documents supporting your correction.
Look for patterns that could explain the decision. Several missed payments may point to repayment history, while a large monthly debt burden may affect affordability. A mismatch between your declared income and supporting records could also raise questions. Distinguish these issues from an isolated data error before deciding whether to reapply.
For a focused review, create a simple record with three columns: the lender’s stated reason, the information supporting it and the next action. For example, pair “income could not be verified” with the relevant payslip and bank statement. Pair “credit information concern” with the report entry and any evidence that it is wrong. This keeps your follow-up precise.
If you find incorrect credit information, dispute the entry through the process for correcting your report. Identify the specific account or item, explain what is inaccurate, and include documents supporting your claim. Keep a copy of what you submit and the response. Don’t assume the correction is complete until it appears on the updated report.
Once you understand the reason, choose a next step that addresses it directly. Correct an application error, resolve an inaccurate report entry, or review affordability if debt or income was the concern. Reapplying without addressing the issue gives the lender little new information to assess. A documented correction makes your next application clearer.
Carz World Pte: Pre-Owned Cars
Carz World Pte Ltd offers pre-owned cars for drivers reconsidering their vehicle choice after a loan rejection. If the lender’s decision points to affordability, compare vehicles with your revised budget to help decide what loan amount to consider next. Focus on a payment that fits your income and existing commitments, rather than stretching your budget for a particular car.
Explore Carz World Pte Ltd’s pre-owned car range when you’re ready to assess vehicle options alongside your budget. Carz World Pte Ltd also offers brand new cars and car rental to suit different needs.
Contact Carz World Pte Ltd or visit its website to explore your options.
Choose a vehicle plan that fits your next step
A financing setback can be a useful opportunity to reassess what kind of transport suits your needs now. If you’re considering what to do if my car loan application is rejected, look beyond the original purchase plan and decide what would make your next choice manageable. Your preferred vehicle, monthly budget and timing can all shape that decision.
Carz World Pte Ltd offers pre-owned cars, brand new cars and car rental. These options can help you consider a different vehicle or a temporary alternative while you review your finances. Choose the direction that best matches your current plans, rather than taking on a commitment that strains your budget.
For a practical next step, explore the available options and decide which fits your needs. Contact Carz World Pte Ltd to discuss your vehicle plans. A clear choice today can help you move forward with greater confidence.
Frequently Asked Questions
What can you do if your loan is turned down?
Pause before making another application and identify what needs attention first. For example, if your submitted income details don’t match your records, correct the discrepancy before applying again. If the proposed car exceeds your budget, consider a less expensive option or a larger deposit. You can also compare alternatives, but weigh their repayment obligations and risks carefully before taking on new debt.
What should I do if my car loan application is rejected?
If you’re deciding what to do if my car loan application is rejected, use the lender’s explanation to choose one clear next step. Keep a record of the issue and any correction you make. For example, if you entered an application field incorrectly, update it and use matching documents. If affordability is the concern, revise your vehicle budget before seeking another assessment.
Why are car loan applications rejected in Singapore?
Applications may be rejected because of high debt relative to income, a low credit score, negative credit report entries or a request to borrow more than the lender considers affordable. Missing or incorrect details can also affect an assessment. For instance, inconsistent employment or income information may make the application harder to evaluate. Identifying the specific concern helps you choose a relevant response.
How can I find out why my car loan was rejected in Singapore?
Review the lender’s denial letter and ask for the reasons within 60 days of the decision. Keep your application reference handy and ask which details or financial factors affected the assessment. Then compare the explanation with your own records. If the lender identifies a credit report issue, obtain your report and dispute information you believe is inaccurate, keeping supporting documents and correspondence together.
What alternatives are there to a car loan in Singapore, and what are their costs and risks?
Options can include a co-signer, in-house dealership financing, a licensed moneylender loan, or a pawnshop loan. Compare interest, repayment terms and who is responsible if payments are missed. Singapore law caps licensed moneylenders’ interest rates at 4% per month. Alternative borrowing can carry risks, so consider what you could lose or become responsible for if you cannot repay.
Disclaimer
This content is provided for general informational purposes only. Readers are encouraged to independently verify important information.
In Same Category
Related by Tags
- What to Do If Your Car Loan Is Rejected and Find Options
- Understanding the MAS Car Loan Restrictions in Singapore (2026)
- Financial Checklist Before Committing to a Car Purchase in Singapore (2026)
- Getting Car Finance as a Freelancer in Singapore: 2026 Guide
- Financial Checklist Before Buying a Car in Singapore: 2026 Expert Guide
- How to Buy a Car in Singapore: The Ultimate 2026 Step-by-Step Guide