Car Downpayment vs Monthly Instalment in Singapore: The 2026 Budgeting Guide
What if the secret to sustainable car ownership in Singapore isn't just about securing the lowest monthly bill, but finding the exact point where your cash flow and savings remain perfectly balanced? We understand that facing the current market is daunting. With Category A COE prices reaching S$133,009 in September 2026 and MAS rules requiring a downpayment of up to 40 percent, the debate over a car downpayment vs monthly installment sg has never been more critical for your wallet.
It's natural to feel concerned about over-leveraging or draining your emergency fund just to get on the road. This guide will help you master the trade-off between high upfront costs and long term monthly commitments. We will break down current MAS regulations and interest saving strategies to help you build a balanced budget that protects your long term financial health while keeping your car ownership dreams within reach. By the end of this article, you will have a clear strategy to minimize your total interest paid and find a monthly commitment that fits your lifestyle without unnecessary stress.
Key Takeaways
- Understand how your car's Open Market Value (OMV) dictates whether you need a 30% or 40% minimum downpayment under current MAS regulations.
- Learn how increasing your upfront payment can significantly reduce the total interest paid over a standard seven-year loan tenure.
- Master the trade-off between a car downpayment vs monthly installment sg to ensure your vehicle remains a sustainable part of your monthly budget.
- Discover how leveraging vehicle consignment or trade-ins can effectively fund your next downpayment without depleting your cash reserves.
- See how professional guidance helps you navigate the financing maze to secure competitive loan packages tailored to your specific financial profile.
The Singapore Car Loan Landscape: Downpayment and Instalment Basics
Understanding the basic mechanics of car financing is the first step toward sustainable ownership. In Singapore, a car downpayment is the initial cash or trade-in value you must pay upfront before the loan covers the remaining balance. Monthly instalments are the recurring payments you make to the lender, comprising both the principal loan amount and the interest. Balancing a car downpayment vs monthly installment sg involves more than just looking at your bank balance; it requires a deep dive into how Singapore's specific regulations shape your buying power.
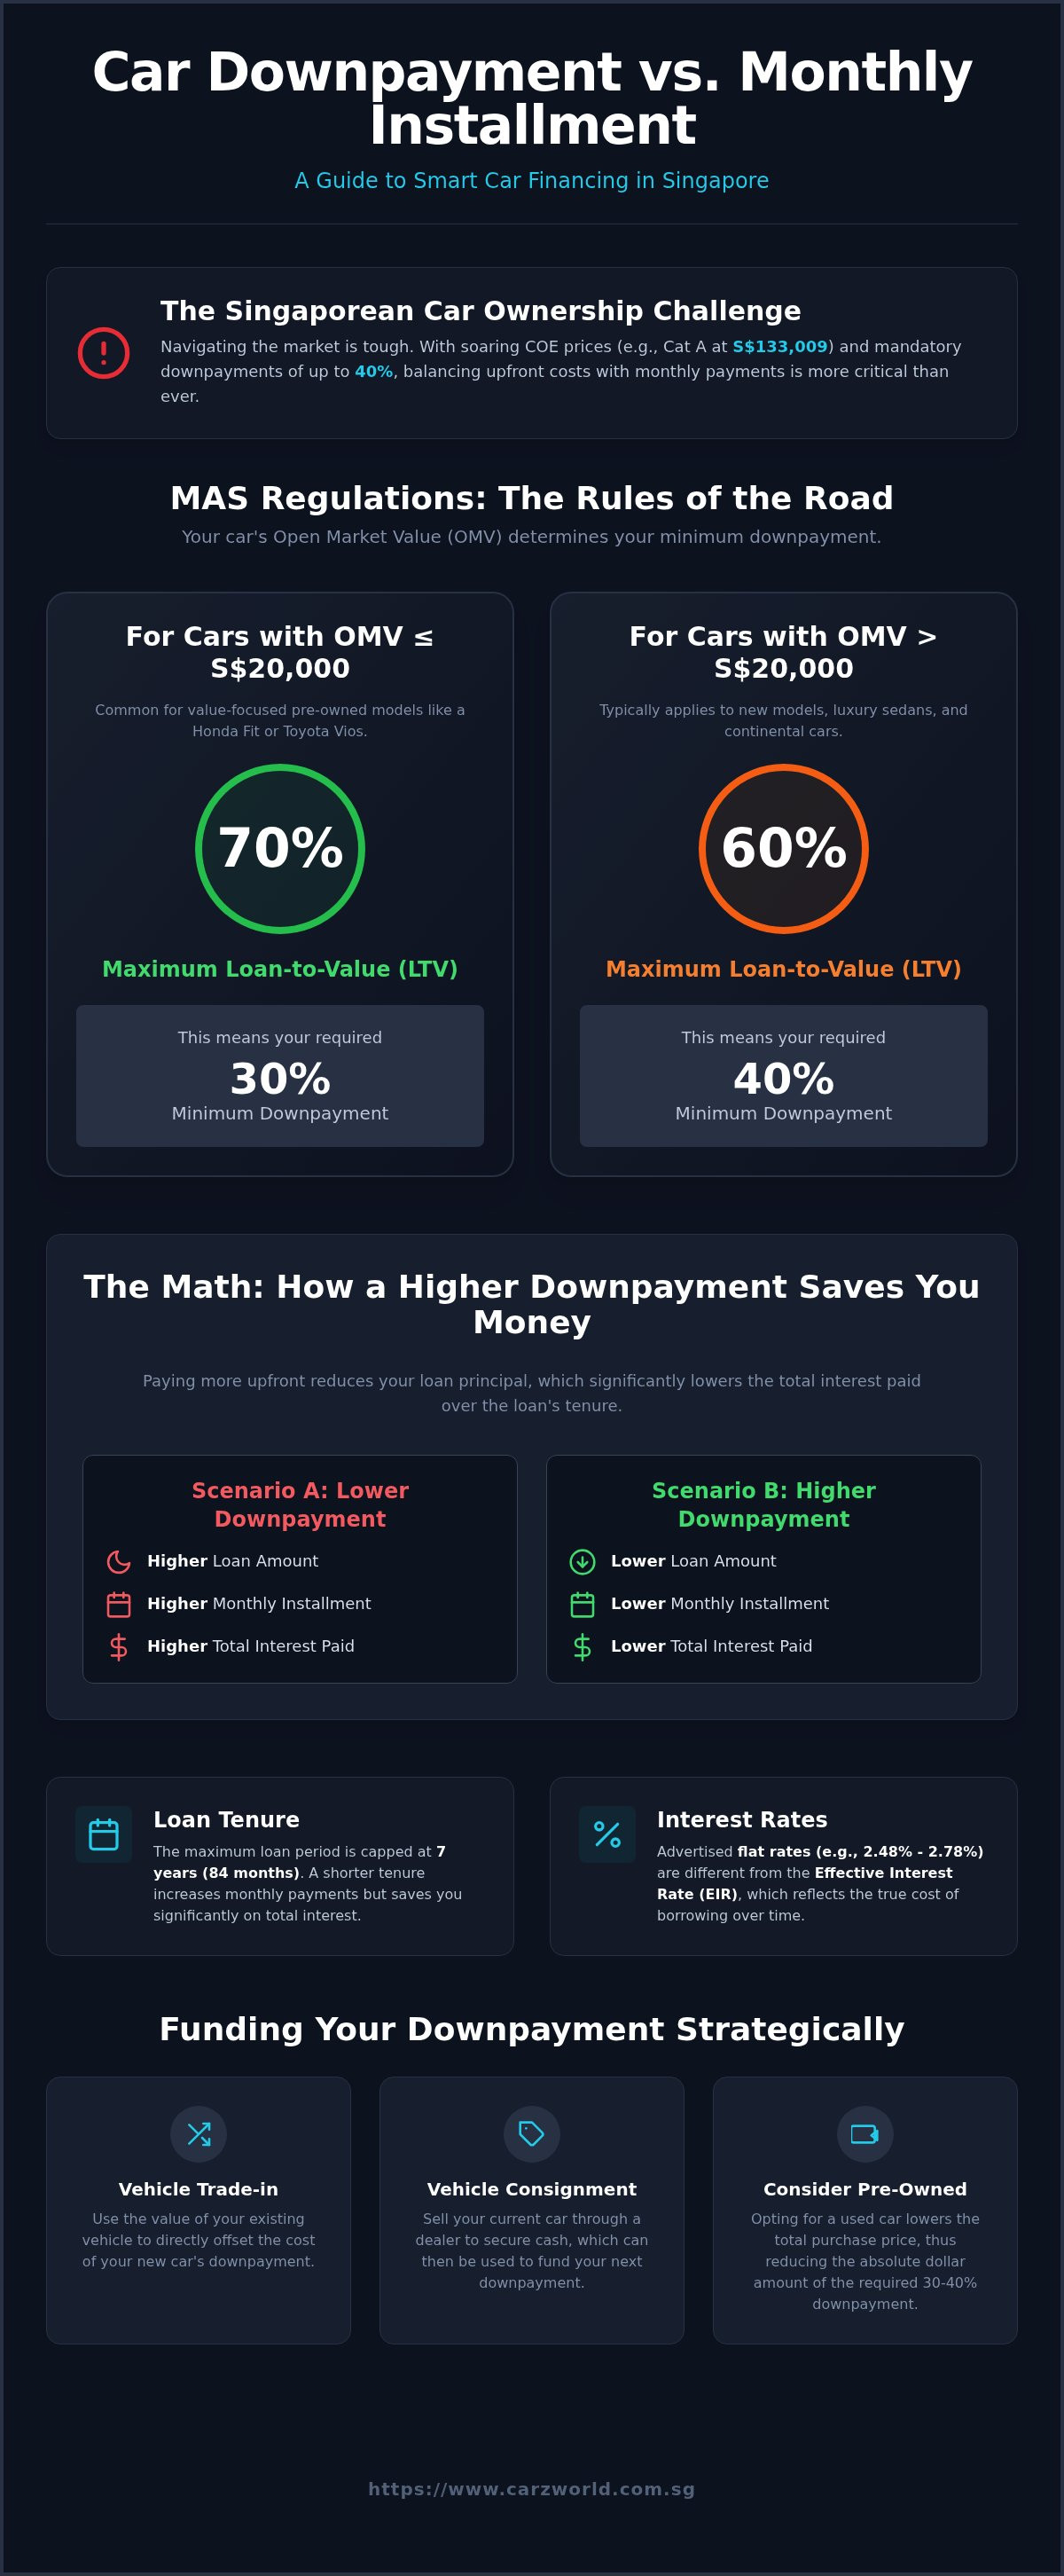
The Monetary Authority of Singapore (MAS) sets strict rules to prevent over-leveraging. These rules dictate the maximum Loan-to-Value (LTV) ratio you can secure. If a car's Open Market Value (OMV) is S$20,000 or less, you can borrow up to 70 percent, requiring a 30 percent downpayment. For cars with an OMV above S$20,000, the LTV drops to 60 percent, meaning you must provide a 40 percent downpayment. This high entry cost makes the upfront versus monthly debate unique to our market, as the initial cash outlay is often the biggest hurdle for buyers.
The Role of the Certificate of Entitlement (COE)
Unlike other markets where the car's sticker price is the primary concern, Singaporean buyers must account for the Certificate of Entitlement (COE). This certificate is bundled into the total purchase price, often making up more than half the cost. As of the first bidding in September 2026, Category A COE prices sit at S$133,009, while Category B is S$135,001. Because your downpayment is a percentage of the total price including COE, these high premiums significantly inflate the cash you need upfront. Budgeting for a car in 2026 requires a clear-eyed look at these premiums before you even consider the monthly cost.
Key Financial Terms You Must Know
To budget effectively, you must distinguish between the flat interest rate and the Effective Interest Rate (EIR). While many banks currently advertise flat rates around 2.48 percent to 2.78 percent p.a., the EIR represents the actual cost of your loan over time. It accounts for the reducing balance of your principal. Additionally, the maximum loan tenure in Singapore is capped at 7 years. Choosing a shorter tenure reduces total interest but increases your monthly burden. If you want to lower the absolute dollar value of your downpayment, exploring pre-owned cars can be a practical solution, as the lower total price reduces the 30 or 40 percent cash requirement.
MAS Regulations: Understanding LTV Limits and OMV Thresholds
The financial feasibility of owning a car depends heavily on the MAS car loan regulations. These rules use the car's Open Market Value (OMV) as the primary yardstick for how much you can borrow. The Loan-to-Value (LTV) limit is either 60 or 70 percent of the purchase price. This regulatory ceiling creates the fundamental tension in the car downpayment vs monthly installment sg debate. If you can't meet the minimum cash requirement, the monthly repayment amount becomes irrelevant because the transaction cannot proceed.
While the downpayment is fixed by OMV, your monthly burden is dictated by the 7-year maximum loan tenure. Spreading the cost over 84 months is the standard approach to keep instalments manageable. However, this long tenure means you'll pay more interest over time. If you choose a shorter tenure to save on interest, your monthly commitment rises sharply. Finding the right balance requires understanding which bracket your desired car fits into.
OMV ≤ $20,000: The 70% Loan Rule
Cars with an OMV of S$20,000 or less qualify for the 30 percent downpayment requirement. This category is the sweet spot for many first-time buyers and those looking for value. Many entry-level pre-owned cars fall into this bracket. For example, a used Honda Fit or a Toyota Vios often has an OMV below this S$20,000 threshold. By choosing these models, you secure a 70 percent LTV, which keeps your initial cash outlay lower. It's a practical way to enter the market without draining your total savings.
OMV > $20,000: The 60% Loan Rule
When a car's OMV exceeds S$20,000, the LTV drops to 60 percent. This means you must provide a 40 percent downpayment upfront. This rule typically applies to brand-new models, luxury sedans, and continental cars. The 10 percent jump in the required downpayment can represent tens of thousands of dollars. Despite the higher hurdle, high-OMV cars often hold their value better or offer superior features. If you have the capital, paying a 40 percent downpayment reduces your total loan amount, which naturally lowers the monthly interest you'll accrue.
If you are unsure where a specific model falls, the team at Carz World can help you calculate the exact OMV and LTV for your preferred vehicle.
The Math of Ownership: How Downpayment Affects Total Interest
The financial impact of your initial payment extends far beyond the first day of ownership. There is a direct inverse relationship between your upfront cash and your long term costs. When you increase your downpayment, you reduce the principal amount of your loan. Because interest is calculated based on this principal, a larger payment today leads to significant savings over the next seven years. This mathematical reality is the foundation of the car downpayment vs monthly installment sg trade-off; every dollar paid now is a dollar that doesn't accrue interest later.
Finding the "Sweet Spot" involves balancing your immediate liquidity with your desire for low debt. For example, paying 10 percent more than the minimum required downpayment can save you thousands in total interest over a standard tenure. While a 7-year loan offers the lowest monthly commitment, a 5-year tenure significantly reduces the total cost of the car. If your monthly budget allows, a shorter tenure combined with a higher downpayment is the most efficient way to own a vehicle in Singapore.
The Cost of Borrowing in 2026
In the current market, bank interest rates typically range from 2.78 percent to 3.50 percent p.a. for brand new cars. It is vital to understand the "Rule of 78," a method lenders use to calculate interest that front-loads your payments. This means you pay more interest in the early years of your loan. If you plan to sell your car before the tenure ends, a higher initial downpayment protects you from "negative equity," where your car's market value is lower than your remaining loan balance.
Opportunity Cost: Should You Keep Your Cash?
Deciding whether to pay more upfront requires looking at opportunity cost. In Singapore, your cash could be earning 2.5 percent in your CPF Ordinary Account or potentially more in fixed deposits. If your car loan interest rate is 2.78 percent, the "cost" of keeping that cash is the 0.28 percent difference. However, liquidity is equally important. A common guide to buying a car suggests that you should never empty your savings for a downpayment. Maintaining an emergency fund is more critical than saving a few hundred dollars in annual interest.
For those looking to balance these costs, choosing from a range of pre-owned cars can lower the absolute loan amount, making both the downpayment and the monthly interest more manageable. This approach allows you to stay within MAS limits while preserving your cash for other investments or unforeseen expenses.
Strategic Budgeting: Trade-ins, Consignment, and Total Costs
Many buyers focus solely on their bank balance when calculating a car downpayment vs monthly installment sg. However, your existing vehicle is often your most powerful financial tool. By using your current car as a "downpayment engine," you can bridge the gap between your savings and the MAS-mandated cash requirements. This strategy effectively lowers the amount you need to borrow, which in turn reduces your monthly burden and total interest paid.
Choosing between consignment and a direct purchase is a critical decision for your budget. Consignment typically allows you to set a higher asking price, potentially yielding a larger sum to put toward your next downpayment. While it takes longer than an immediate trade-in, the extra S$3,000 to S$5,000 gained could significantly lower your future monthly instalments. A direct purchase offers speed and a guaranteed loan discharge, providing immediate peace of mind if you need to switch vehicles quickly.
Maximising Your Trade-in Value
To get the best possible credit toward your new downpayment, presentation is key. Ensure your service records are organized and the vehicle is professionally groomed. Small details like fixing minor dents or replacing worn tyres can improve your valuation by more than the cost of the repairs. You can find out how much your car is worth today through our valuation service to start your planning. We handle the complex paperwork trail, including the discharge of your existing bank loan, making the transition to your next vehicle seamless. This professional oversight ensures that the trade-in value is applied accurately to your car downpayment vs monthly installment sg calculation.
The '30% Rule' for Monthly Car Expenses
Financial prudence suggests that your total car-related expenses should not exceed 30 percent of your monthly take-home pay. Your "true monthly commitment" is much higher than just the bank instalment. You must account for recurring costs such as comprehensive insurance, annual road tax, season parking, and ERP charges. If a brand-new model pushes you past this 30 percent threshold, consider pre-owned cars. These vehicles offer a lower entry point, ensuring your lifestyle remains sustainable without financial strain. Balancing these "hidden" costs is just as important as the loan itself.
If you're ready to see how your current vehicle can offset your next purchase, contact Carz World today for a professional assessment of your trade-in options.
Carz World: Tailored Financing for Your Next Move
Finding the right vehicle shouldn't be a stressful logistical puzzle. At Carz World Pte Ltd, we believe that a professional, customer-centric approach is the only way to simplify the complexities of car ownership. We provide access to a wide range of competitive loan packages through our extensive partner network. This allows us to find terms that align with your specific financial goals. Our team handles the integration of insurance, road tax, and ownership transfer, making the entire process feel seamless and efficient from start to finish.
Choosing from our Certified Pre-Owned collection is one of the smartest ways to lower your LTV hurdle. Because these vehicles have a lower total purchase price than brand-new models, the absolute dollar value of your 30 or 40 percent downpayment becomes much more manageable. This strategic choice helps you master the car downpayment vs monthly installment sg trade-off by preserving your cash while still securing a reliable, high-quality vehicle that meets our strict standards.
Expert Guidance from Our Dedicated Personnel
Our experienced staff members are here to help you manage the technicalities of MAS LTV limits and OMV calculations. We offer personalized budgeting sessions where we sit down with you to find your ideal downpayment vs. instalment ratio. We don't believe in high-pressure sales tactics. Instead, we focus on building long-term trust and reliability. Many of our clients frequently mention specific team members in their feedback, highlighting the importance of the individual, high-quality service that defines our business model. We want you to feel confident that your financial commitment is sustainable for years to come.
From Brand New to Export: Comprehensive Services
Our expertise extends across every stage of the car ownership lifecycle. You can explore our Brand New Parallel Import inventory if you're looking for the latest models with competitive pricing. When you're eventually ready to change cars again, our export services ensure you get the best possible value for your current vehicle. For those who aren't quite ready for a large upfront downpayment, we also offer flexible car rental options. These services allow you to stay mobile without the immediate burden of a long-term loan. Whatever your stage in life, we have a solution that fits your budget and your needs.
Drive Away with Financial Confidence
Finding the right balance doesn't have to be a guessing game. By mastering the car downpayment vs monthly installment sg trade off, you protect your savings while enjoying the mobility you need. Your car's OMV dictates your minimum cash outlay, but your loan tenure and downpayment amount ultimately decide how much interest you pay over time. Using strategic tools like trade ins or consignment can effectively lower your entry barrier without draining your emergency fund.
At Carz World, we specialize in making these complex logistics feel seamless. Our expert staff members, highlighted in over 100 positive reviews, provide transparent OMV and LTV breakdowns to ensure you make an informed choice. With our in house financing and insurance experts, we identify competitive packages that suit your lifestyle and financial goals.
Book a Financial Consultation with Carz World Today to start your journey. We look forward to helping you find the most sustainable way to own your next vehicle.
Frequently Asked Questions
What is the minimum downpayment for a car in Singapore in 2026?
The minimum downpayment depends on the car's Open Market Value (OMV). For vehicles with an OMV of S$20,000 or less, you must pay at least 30 percent upfront. If the OMV exceeds S$20,000, the requirement increases to 40 percent. This cash outlay is a legal requirement under MAS regulations. Meeting these thresholds is the first step in the car downpayment vs monthly installment sg calculation for any buyer in the current market.
Can I use my CPF to pay for a car downpayment or monthly instalments?
No, you cannot use your Central Provident Fund (CPF) savings for any car-related expenses. This includes the initial downpayment, monthly instalments, or related costs like insurance and road tax. CPF funds are strictly reserved for retirement, housing, and healthcare needs. You must ensure you have sufficient cash or trade-in value from your current vehicle to cover the upfront costs and the recurring monthly commitments throughout your loan tenure.
How does the OMV of a car affect my maximum loan amount?
The Open Market Value (OMV) serves as the primary threshold for your maximum Loan-to-Value (LTV) ratio. A lower OMV of S$20,000 or less allows you to borrow up to 70 percent of the purchase price. Conversely, a higher OMV above S$20,000 limits your borrowing to 60 percent. This regulatory structure ensures that buyers of luxury or higher-end vehicles provide a larger equity stake upfront, reducing the total debt carried over seven years.
Is it better to take a shorter loan tenure if I can afford higher instalments?
Choosing a shorter loan tenure is financially beneficial if your monthly cash flow allows it. While a 7-year loan offers the lowest monthly commitment, it results in the highest total interest paid. By opting for a 5-year or 6-year tenure, you reduce the time interest has to accrue. This approach helps you build equity in your vehicle faster and saves you thousands of dollars in the long run, provided the higher instalments don't strain your budget.
What happens if I want to pay off my car loan early?
Early repayment is possible, but it often involves specific costs. Most banks charge an early settlement penalty, typically around 1 percent of the original loan amount. Additionally, because car loans in Singapore use the Rule of 78 for interest calculation, you might find that the interest rebate is lower than expected. It's best to check your specific loan agreement or speak with our financing experts to calculate the exact redemption amount before proceeding.
Does the downpayment include the COE and ARF?
Yes, the downpayment is calculated based on the total purchase price of the vehicle. This price includes the Certificate of Entitlement (COE), Additional Registration Fee (ARF), and the dealer's margin. Because COE prices are currently elevated, often exceeding S$130,000 in late 2026, the absolute dollar value of your 30 or 40 percent downpayment will be significantly higher than the car's basic manufacturing cost alone. This makes upfront budgeting more critical than ever.
Can I get a 100% loan for a car in Singapore?
No, standard car loans in Singapore are strictly regulated by MAS, which mandates a minimum downpayment of 30 or 40 percent. A 100 percent loan is not legally permissible for personal vehicle purchases. While some alternative schemes might exist for leasing or private hire vehicles, they carry different risks and regulations. For a standard private car purchase, you must be prepared to provide the required cash or trade-in value upfront to secure a legal loan.
How do interest rates differ between new and used cars?
Interest rates for brand new cars are generally lower, often ranging from 2.48 percent to 2.78 percent p.a. in the current 2026 market. Pre-owned cars typically command higher rates, often between 3.0 percent and 3.5 percent p.a., as lenders view them as higher risk. However, because used cars have a lower total purchase price, the car downpayment vs monthly installment sg balance might still be more favourable despite the higher rate.
Disclaimer
This content is provided for general informational purposes only. Readers are encouraged to independently verify important information.
In Same Category
- Used Cars for Sale in Tampines: 2026 Buyer's Guide
- Car Downpayment vs Monthly Instalment in Singapore: The 2026 Budgeting Guide
- Check Outstanding Car Finance in Singapore: 2026 Guide
- Parallel Import Singapore: The Ultimate 2026 Buyer’s Guide
- Car Loan Singapore: The Complete 2026 Guide to Financing Your Vehicle
Related by Tags
- Used Cars for Sale in Tampines: 2026 Buyer's Guide
- Car Downpayment vs Monthly Instalment in Singapore: The 2026 Budgeting Guide
- Check Outstanding Car Finance in Singapore: 2026 Guide
- Car Loan Singapore: The Complete 2026 Guide to Financing Your Vehicle
- How Much Salary to Afford a Car in Singapore: 2026 Affordability Guide
- Buying a Used Car in Singapore: 2026 Ultimate Guide
- What is PARF? The Ultimate Guide to Singapore’s Car Rebate System
- Mercedes-Benz EQB 250+ Review: The Ultimate 7-Seater Family EV in Singapore
- Long Term Car Rental Singapore: 2026 Definitive Guide
- How to Buy a Car in Singapore: The Ultimate 2026 Step-by-Step Guide
- Second Hand Hybrid Cars Singapore: The 2026 Value & Inspection Guide
- Cheapest Car in Singapore: The 2026 Guide to Affordable Ownership
- Parallel Import Cars Singapore: 2026 Buyer’s Guide
- Suzuki Swift Singapore: The Ultimate Smart-Money Hatchback Guide 2026
- The Ultimate Toyota Alphard Singapore Guide: Luxury & Performance in 2026
- Sell My Car in Singapore (2026): Complete Guide
- Nissan Qashqai Singapore: Ultimate Buyer’s Guide 2026
- The Ultimate Used Car Buying Guide for Singapore in 2026
- Used Honda Singapore: The Ultimate Buyer’s Guide for 2026
- The Real Cost of Owning a Car in Singapore: 2026 Comprehensive Guide
- Parallel Import Cars in Singapore: The Ultimate 2026 Buyer’s Guide
- Used Toyota Singapore: The Ultimate Buyer’s Guide for 2026
- COE Renewal Singapore: The Ultimate 2026 Guide to PQP, Costs, and Strategy
- Buying a Used Toyota Corolla Altis in Singapore: The 2026 Ultimate Buyer’s Guide
- How to Buy a Used Car in Singapore: The Ultimate 2026 Guide
- Best Budget Used Cars in Singapore: 2026 Value Guide
- Sell My Car in Singapore: The Ultimate 2026 Guide to Getting the Best Price
- Used Honda Fit in Singapore: The Ultimate 2026 Buyer's Guide